What term life insurance actually does
Term life is the simplest kind of life insurance: if you die during the term, it pays your family a tax-free lump sum. No investment account, no complicated riders — just protection while your family needs it most.
Replaces your paycheck
Rent or mortgage, groceries, utilities, car payments — life keeps billing your family even if your income stops. Coverage sized to your income keeps the household running for the years they need to land on their feet.
Keeps the home
The single biggest reason families lose a home after a death is the mortgage with one income gone. A policy sized to the loan balance means your family stays in the home you worked for — nobody has to move in the middle of grieving.
Protects the kids' future
Childcare, school, and the everyday costs of raising children don't pause. Term coverage bridges the years until your kids are grown and supporting themselves — which is exactly why the term usually matches those years.
Covers final costs
Funeral and burial expenses can run into the tens of thousands, due immediately. A policy makes sure your family isn't passing a hat or draining savings at the worst possible moment.
How much coverage do you need?
Move the sliders. This is the same math used in a real consultation — add up what your family would need, and that's your number. The 3D shield beside your total grows and shrinks with it, so you can see the protection change as you work. Drag it to turn it.
What your household would lose each year if you were gone.
Often until the youngest child is grown, or the mortgage is paid down.
Mortgage balance, car loans, credit cards — anything you'd want paid off outright.
Funeral costs, plus a head start on college or trade school for the kids.
This is the amount your family would receive — not a price, and not what you pay.
Illustration only — not a quote and not financial advice. Your real number depends on your full picture; that's what the free consultation is for. Final coverage is subject to carrier underwriting.
Pick a term that matches the need
The term is how long the protection lasts. The right length is the one that covers the years your family is counting on your income. Tap a term to see who it fits.
20-year term — the family-years policy
The most common choice for parents. It covers the stretch from young kids to grown ones — mortgage shrinking, children heading out on their own. If you bought a home or had a child in the last few years, start here.
Annuities, in plain English
An annuity is not an investment account and not a bank account. It's a contract with an insurance company, built for money you're setting aside for later — most often for retirement. There are two main kinds — fixed and variable — and they work very differently. Here's each one, without the jargon.
What a fixed annuity is
You pay money in — one lump sum, or over time — and the insurance company holds it under a contract for a set number of years. The contract credits interest at a fixed rate set in the contract, and the money grows tax-deferred until you take it out. When the time comes, you can withdraw it or turn it into a stream of payments.
It stays out of the stock market
A fixed annuity isn't invested in the market, so its contract value doesn't rise and fall with Wall Street. What it does — the rate, the term, the access rules — is written in the contract itself, in black and white, before you sign.
Who it can fit
Often someone nearing or in retirement who has savings they won't need to touch for several years, who wants those savings out of market swings, and who is comfortable trading quick access for a contract with set terms. It is not the place for money you might need next month — that's what a bank account is for.
The honest trade-offs
Your money is committed for the term of the contract. Taking it out early can mean surrender charges, and withdrawals are taxed as income. An annuity is backed by the insurance company that issues it — so the carrier matters, and the contract matters. We read the actual terms together, in plain English, before you sign anything.
Variable annuities — the other kind
A variable annuity is still a contract with an insurance company, but unlike a fixed annuity, your money goes into market investments inside the contract. That difference changes everything about the risk.
Your money is invested in the market
Inside a variable annuity, your money is placed in investment choices called subaccounts — similar to mutual funds — covering stocks, bonds, and mixes of both. Your contract value rises and falls with those investments. There is no fixed rate and no floor written into the contract: if the market drops, your value drops with it, and you can lose money, including principal.
Growth is tax-deferred, not tax-free
Like a fixed annuity, the money grows tax-deferred — you don't pay tax on the growth each year. When you take money out, the earnings are taxed as ordinary income, and withdrawals before age 59½ can also carry a federal tax penalty. Turning the contract into a stream of income payments is an option here too.
The fees are higher — read them closely
Variable annuities typically charge more than fixed annuities: mortality and expense charges, administrative fees, the costs of the subaccounts themselves, and extra charges for any optional riders you add, such as a guaranteed income or death benefit. Surrender charges can also apply if you take money out early in the contract term. Every one of those charges is in the prospectus and the contract — we go through them line by line, in plain English, before you sign anything.
Who it can fit — and who it usually doesn't
A variable annuity is a security, and it's generally for a long horizon: someone who has already used simpler tax-advantaged accounts, wants tax-deferred market growth, understands the value can go down, and won't need the money for years. If market losses would keep you up at night, or the money is needed soon, it is usually the wrong tool — a fixed annuity or a plain bank account fits better. If it doesn't fit, I'll say so.
The process, if an annuity fits
Same as everything here: three steps, no pressure, and no money ever passes through my hands.
Book a free consultation
We talk by phone or video about where you stand — what you've set aside, when you'll need it, and what you want that money to do for you in retirement.
Get a recommendation, in plain English
If an annuity fits your situation, I'll lay out the contract terms plainly — the period, the charges, the access rules — and how it compares with simply leaving the money where it is. If it doesn't fit, I'll say so.
Apply directly with the carrier
Your application goes straight to the insurance company, and your premium is paid directly to the carrier — never to me. The contract is issued by the carrier, and your money sits with them.
Free consultation · No obligation · CA Life Insurance License #4584991
Educational information only — not financial, tax, or legal advice. Annuity features, terms, charges, and availability are set by the issuing carrier's contract.
How it works
Three steps, no pressure, and no money ever passes through my hands.
Book a free consultation
Pick a time that suits you. We'll talk by phone or video — where your family stands, what you owe, what you want protected.
Get your number, in plain English
We size the coverage together using the same math as the estimator above, and pick a term that matches your family's timeline. Questions welcome — all of them.
Apply directly with the carrier
Your application and your premium go straight to the insurance company — never to me. That's by design: your money should only ever sit with the carrier holding your policy.
About James
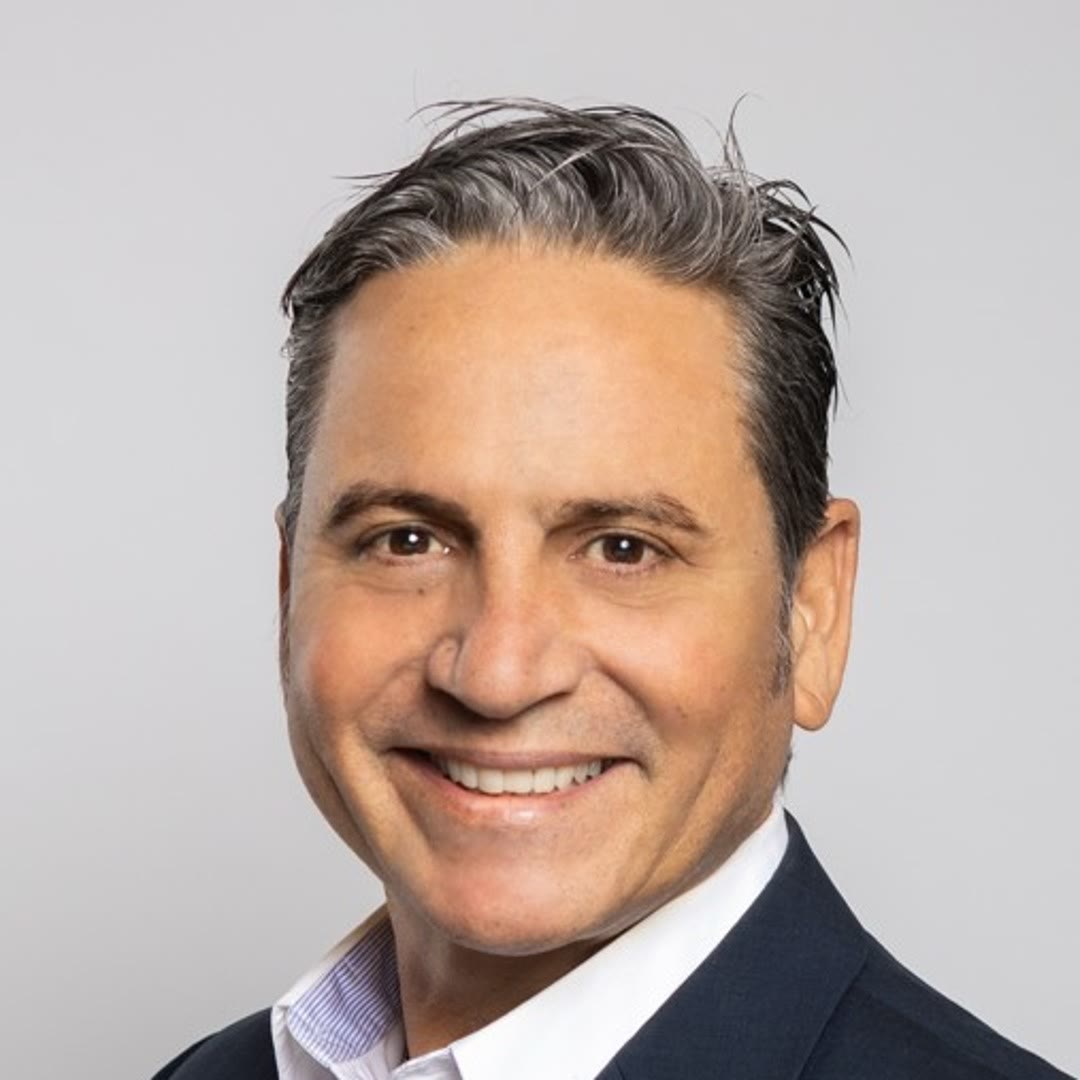
I'm James Timbrello — Jimmy to most people. I run Timbrello Financial & Insurance Services out of Monterey Park, serving families across Los Angeles and Orange County.
I came to insurance the same way I approach everything else in my working life: faith and family first, straight talk always. When we talk, you'll get the honest picture — what a policy covers, what it doesn't, and what I'd tell my own family to buy. If term life isn't right for your situation, I'll say so.
I'm a licensed California life insurance agent, and I keep it deliberately simple: term life, explained clearly, with your premium paid directly to the carrier. No pressure, no jargon, no surprises.
- CA Life Insurance License #4584991
- Consultations by phone or video, across LA & Orange County
Questions people ask me
It's life insurance for a set number of years — 10, 20, or 30 are typical. If you die during that term, the carrier pays your named beneficiaries a lump sum, generally free of federal income tax. If the term ends and you're still here (the outcome everyone wants), the policy simply expires. Because it's pure protection with no investment component, it's the most affordable way to carry a large amount of coverage during the years your family depends on your income.
A common starting point is 10–15 times your annual income, adjusted for your mortgage, other debts, and how many years your children still have at home. The estimator on this page runs that math with your own numbers. In the consultation, we refine it together — existing savings, a spouse's income, and any coverage through work all count.
No — and that's deliberate. Your premium goes directly to the insurance carrier, always. I never collect or hold client money for premiums. Agents are compensated by the carriers; it costs you nothing extra to work with me instead of going it alone.
It depends on the carrier and the amount of coverage. Many policies today are issued with a short health questionnaire and records review instead of an exam; larger amounts may still require one. In the consultation I'll tell you honestly what to expect for your situation before you apply — no surprises.
I'm based in Monterey Park and work with families throughout Los Angeles County and Orange County. Most consultations happen by phone or video, so wherever you are in those counties, we can talk.
Thirty minutes. That's all it takes to know your number.
Book a free consultation, or just call. You'll talk to me — not a call center, not a bot.
Prefer to write first? Email me at james@t-financial.com
Know a family with a new baby, a new home, or one income carrying it all? Send them my way — a referral is the highest compliment my business can get, and I'll take care of them the same way I'd take care of you.